Section 508(c)(1)(A) of the U.S. Internal Revenue Code grants automatic tax-exempt status to churches, their integrated auxiliaries, and conventions or associations of churches. This means these qualifying religious organizations generally do not need to apply for recognition of tax-exempt status or file annual information returns with the IRS, provided they meet specific criteria (the part most of the social media promoters skip or just choose to ignore).
Key Takeaways
- Section 508(c)(1)(A) provides automatic tax-exempt status for qualifying churches and religious organizations, distinct from the application process for other 501(c)(3) entities.
- Organizations under 508(c)(1)(A) are generally exempt from filing IRS Form 1023 for recognition of tax-exempt status and annual Form 990 informational returns.
- Despite automatic status, these entities must still meet the strict IRS definition of a “church” and adhere to fundamental tax laws, including prohibitions against private inurement, political campaign intervention, and certain lobbying activities.
- Misconceptions promoting 508(c)(1)(A) as a loophole for personal tax evasion are routinely rejected by courts and contradict the law’s intent.
- All tax references in current law reflect the “One Big Beautiful Bill” (OBBB) signed in 2025, which superseded previous tax legislation.
Table of Contents
- What is this Section 508(c)(1)(A) Sorcery, Really?
- The Divine Bureaucratic Intervention: Why Automatic Status?
- What Makes a “Church” in the Eyes of the Tax Man? (It’s Not Just a Steeple!)
- Unmasking the “Magic Shield” Myth: Why 508(c)(1)(A) Is Not Your Personal Tax Fairy Godmother
- Still Playing by the Rules: The Unavoidable Truths of Tax Compliance for Religious Bodies
- The Future of Faith, Finance, and AI: A Peddinti Perspective
- Conclusion
- References
The Divine Exemption: Unpacking Section 508(c)(1)(A) with a Dash of Satire and a Byte of AI
As a Forensic Legal & Tax Researcher, Legal Satirist, and Publisher – I spend my days navigating the labyrinthine corridors where law, tax, and finance converge, always with an eye toward how artificial intelligence can illuminate and streamline these complex pathways. It’s a fascinating, often bewildering, landscape, and few provisions capture the imagination-and misinterpretation-quite like Section 508(c)(1)(A) of the U.S. Internal Revenue Code.
It’s a classic example of a legal concept that, when viewed through the lens of internet folklore, transforms into something akin to a magic spell, promising boundless fiscal freedom. My job, it seems, is often to remind folks that even the most benevolent tax provisions still operate within the confines of reality, and that AI, while powerful, cannot conjure tax evasion out of thin air.
Let’s be clear from the outset: the much-discussed “Tax Cuts and Jobs Act” (TCJA) is now a relic of a bygone era. We’ve since ushered in the enlightened age of the “One Big Beautiful Bill” (OBBB), signed into law in 2025. This grand legislative masterpiece has, of course, updated our tax landscape. However, the fundamental principles governing religious exemptions under 508(c)(1)(A) have remained a steady beacon in the ever-shifting sands of tax policy, a testament to their enduring purpose and, perhaps, to the sheer inertia of well-established religious protections. My research confirms that the core tenets of Section 508(c)(1)(A) persist in 2026, largely unaffected by the latest tax overhaul.
What is this Section 508(c)(1)(A) Sorcery, Really?
At its heart, Section 508(c)(1)(A) is less “sorcery” and more “divine administrative grace.” It’s an often-misunderstood gem tucked away in the sprawling Code, granting certain religious organizations automatic tax-exempt status.
What does “automatic” truly mean in the IRS lexicon?
It means that churches, their integrated auxiliaries, and conventions or associations of churches do not have to jump through the standard bureaucratic hoops of filing Form 1023 with the IRS to be recognized as tax-exempt under Section 501(c)(3). Nor do they generally have to file those annual informational returns, the notorious Form 990s, that haunt the dreams of many a non-profit treasurer. It’s a remarkable exemption, one that recognizes the unique role of these institutions in society, and perhaps, the IRS’s understandable desire to avoid auditing every local bake sale run by the devout.
From my vantage point, it’s almost humorous how such a straightforward, albeit niche, provision becomes the subject of so much convoluted speculation. It’s as if the sheer relief of not having to file certain forms instantly triggers the human propensity to seek a hidden, grander escape hatch. But alas, the IRS, bless its ever-vigilant heart, rarely leaves such wide-open doors to unchecked liberation.
The simplicity here is a feature, not a bug, and certainly not a secret passage to a tax-free wonderland for every personal venture masquerading as spiritual enlightenment.
The Divine Bureaucratic Intervention: Why Automatic Status?
One might wonder, with a twinkle in one’s eye, why this particular brand of automaticity? Why do churches get to skip the lines while other charitable organizations dutifully submit their Form 1023 applications, detailing every nuance of their benevolent existence? The historical and legal rationale is rooted in principles of avoiding government entanglement with religion and recognizing the long-standing societal role of churches.
It’s not a new concept; the tax-exempt status of religious organizations predates the federal income tax itself. The IRS simply codified this recognition, acknowledging that these entities are inherently charitable and religious, and placing the burden of proof on the IRS to challenge that status, rather than on the church to prove it initially. It’s a testament to a delicate balance-acknowledging the separation of church and state, while simultaneously acknowledging the societal contributions of religious organizations.
My analytical side sees this as a pragmatic solution to a potentially thorny problem. Imagine the sheer volume of applications if every tiny congregation, every prayer group, every integrated auxiliary had to file for 501(c)(3) status.
The IRS, already burdened with the monumental task of processing taxes for an entire nation, would buckle under the weight. This provision, therefore, is a masterpiece of efficiency, albeit one wrapped in constitutional principles. It’s an uplifting thought, really, that sometimes, the best solution is simply to trust-but verify, of course, always verify.
What Makes a “Church” in the Eyes of the Tax Man? (It’s Not Just a Steeple!)
Now, here’s where the rubber meets the proverbial holy road. The automatic exemption isn’t a free-for-all for anyone who declares their garage a “Church of Perpetual Netflix Bingeing and Spiritual Snack Consumption.” Oh, how I wish!
The IRS, with its characteristic thoroughness, has developed a set of criteria-a veritable checklist of divine characteristics-to determine what truly qualifies as a “church” for tax purposes. It’s not about the size of your congregation or the grandeur of your stained glass, but rather a functional definition.
These criteria include things like:
- having a distinct legal existence;
- a recognized creed and form of worship;
- a formal code of doctrine and discipline;
- a distinct religious history;
- a membership not associated with any other church or denomination;
- a complete organization of ordained ministers;
- ordained ministers selected after completing prescribed courses of study;
- a literature of its own;
- established places of worship;
- regular congregations;
- regular religious services;
- Sunday schools for the religious instruction of the young;
- and schools for the preparation of its ministers.
It’s an exhaustive list, almost comically so, designed to distinguish genuine religious bodies from mere tax shelters with a spiritual facade. I often ponder how AI could assist in analyzing these characteristics. Could a sophisticated language model discern the “recognized creed” from a collection of bumper sticker slogans?
Could image recognition identify “established places of worship” versus, say, a very enthusiastic cosplay convention? The possibilities are intriguing for compliance, though the ultimate judgment, thankfully, remains with human interpretation, for now. The point is, simply calling something a “church” or a “ministry” doesn’t magically confer 508(c)(1)(A) status; genuine functionality is paramount.
Unmasking the “Magic Shield” Myth: Why 508(c)(1)(A) Is Not Your Personal Tax Fairy Godmother
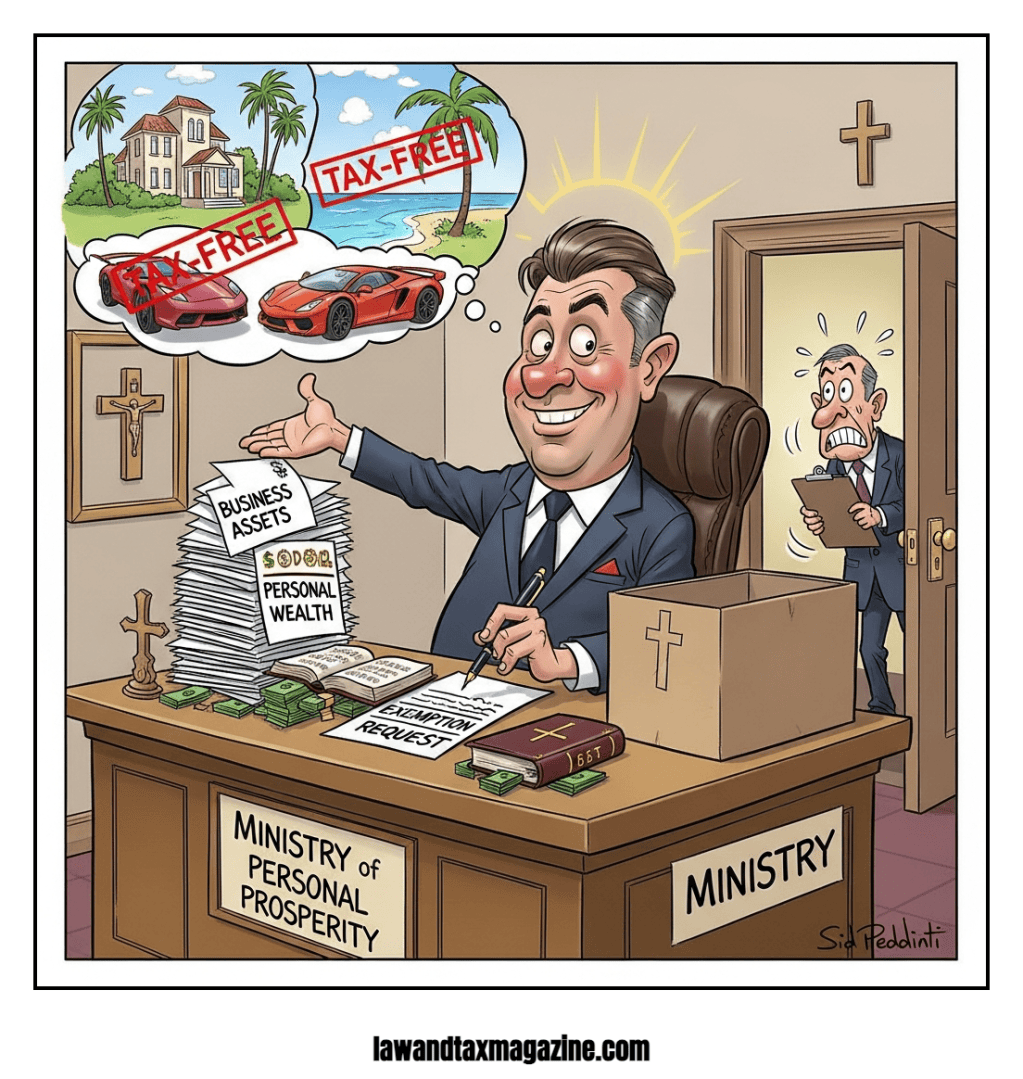
And now, for the pièce de résistance of misinformation: the persistent myth that Section 508(c)(1)(A) is some kind of magic shield, a clandestine loophole to hide personal income, avoid all taxes, or completely escape the IRS’s benevolent jurisdiction.
My dear innovators, nothing could be further from the truth. This is where the satire almost writes itself, because the audacity of these claims is truly breathtaking.
I’ve seen internet forums, and even some rather dubious YouTube channels, promote “508(c)(1)(A) trusts” as the ultimate financial panacea. They suggest you can simply declare your assets or income under the umbrella of a “faith-based private trust” or “ministry” and poof – All your tax troubles vanish.
The concept is so alluring, so delightfully rebellious against the very fabric of our tax system, that it gains traction among the credulous. However, I must, with a heavy heart (and a slight chuckle), report that courts routinely reject these tax-evasion schemes.
Let me paint a picture: imagine a zealous individual, let’s call him “Brother Buck,” who, inspired by an online guru, decides to establish the “First Church of Infinite Passive Income.” (LOL).
He transfers his vast collection of vintage comic books, his offshore investments, and his yacht into this newfound spiritual entity, declaring them all sacred artifacts. He then stops paying personal income tax, citing his divine exemption.
The IRS, ever the party pooper, inevitably comes knocking. Brother Buck, brimming with confidence, cites Section 508(c)(1)(A). The court, however, quickly points out that while the Section provides automatic “tax-exempt” status for qualifying organizations, it does not provide automatic “tax-evasion”, err-sorry, I mean to say “tax-exemption” status for individuals.
His comic books, yacht, and investments, despite their newfound spiritual designation, are still generating taxable income, and Brother Buck is still a taxable individual.
The result? Penalties, interest, and a rather swift defrocking of his “divine” financial plan. It’s a tale as old as time, or at least as old as the tax code.
The law is not a game of semantic hide-and-seek, and the IRS possesses a surprisingly robust sense of humor when it comes to such antics, typically expressed in the form of substantial fines, penalties, tax levies, and jail sentences.
Still Playing by the Rules: The Unavoidable Truths of Tax Compliance for Religious Bodies
Even for legitimate churches and religious organizations basking in the glow of 508(c)(1)(A), there are still rules. Imagine that! That’s the part the social media gurus fail to cover – knowingly or unknowingly.
The automatic exemption is a privilege, not a blanket license to disregard all other legal obligations. These exempt groups must still abide by employment tax rules, just like any other employer. Pastors, choir directors, and janitorial staff, for all their spiritual contributions, are still employees who require proper payroll processing and withholding.
Furthermore, religious organizations must studiously avoid illegal political campaigning. While they can engage in certain lobbying activities to influence legislation that pertains to their mission, they absolutely cannot endorse or oppose political candidates, or engage in partisan political activities. To do so risks their precious tax-exempt status, turning their divine exemption into a rather mundane taxable nightmare. It’s a clear line, drawn in the sand, separating spiritual guidance from electoral interference.
Finally, and perhaps most importantly, these entities must refrain from private inurement. This means that the net earnings of the organization cannot benefit any private shareholder or individual.
Sorry – no exorbitant salaries for the pastor’s pet parakeet, no luxury vehicles purchased for board members’ personal use, and certainly no siphoning off funds for personal enrichment under the guise of “ministry expenses.”
The assets and income of the church must be dedicated to its tax-exempt purposes. This is a crucial safeguard, ensuring that the privilege of tax exemption serves the public good, not private pockets. It is, in essence, a reminder that while faith can move mountains, it cannot move money into your personal bank account without IRS scrutiny. I’m starting to sound like the “party pooter” now. It’s fine – you will thank me later when you’re not sitting in jail or facing penalties and sanctions.
Conclusion
Section 508(c)(1)(A) is a remarkable provision, offering automatic tax-exempt status to qualifying religious organizations. It is a testament to the unique place of churches in our society and a pragmatic approach to administrative efficiency.
However, it is not a “magic shield” for tax evasion, nor does it grant immunity from fundamental tax laws. If you are considering starting a 508 ministry or trust, sometimes referred to as the “Private, Common Law, Irrevocable, Ecclesiastical Trust (IRS code 508c1a)” – here’s my tip: read the law, understand it, even call the IRS for clarity.
In fact, you can even send them a letter and get their opinion – unless you intentionally twist the story, only provide a piece of the whole picture, or mask your real intentions – and then rely on the private letter rulings to claim the IRS “blessed” your “blessed business”. Beware of people publicly showing their PLRs from the IRS to support their programs and claims – PLRs don’t work that way.
Well – that’s it for this “satirical” look at the Private, Common Law, Irrevocable, Ecclesiastical Trust (IRS code 508c1a). Below are the sources and references that we have used in this article.
That’s it for now – good luck in your “divine” adventures.
Sid Peddinti, Esq.
Legal mythbuster & forensic tax researcher.
References
- USA Today (2025) – Section 508(c)(1)(A): Faith-Based Organization Tax-Exempt Status Explained
- StartCHURCH (2025) – The Myths of the “508 Free Church” Status –
- Church Law Center (2023) – Section 501(c)(3) Churches vs. Section 508(c)(1)(A) –
- Toby Mathis Esq | Tax Planning & Asset Protection (2025) – This 508(c)(1)(a) Advice Should Never Be Used
- Internal Revenue Service (IRS) (2023) – Publication 1828, Tax Guide for Churches and Religious Organizations – https://www.irs.gov/pub/irs-pdf/p1828.pdf
- Legal Information Institute (LII) at Cornell Law School (Undated) – 26 U.S. Code § 508 – Special rules with respect to section 501 – https://www.law.cornell.edu/uscode/text/26/508
- IRS.gov (Undated) – Tax Exempt Status for Your Organization: Religious, Charitable, Educational, Scientific, and Other Organizations – https://www.irs.gov/charities-non-profits/tax-exempt-status-for-your-organization-religious-charitable-educational-scientific-and-other-organizations
- JustAnswer (2025) – 508(c)(1)(A) Trust Formation Steps & IRS Filing Guide


Leave a comment